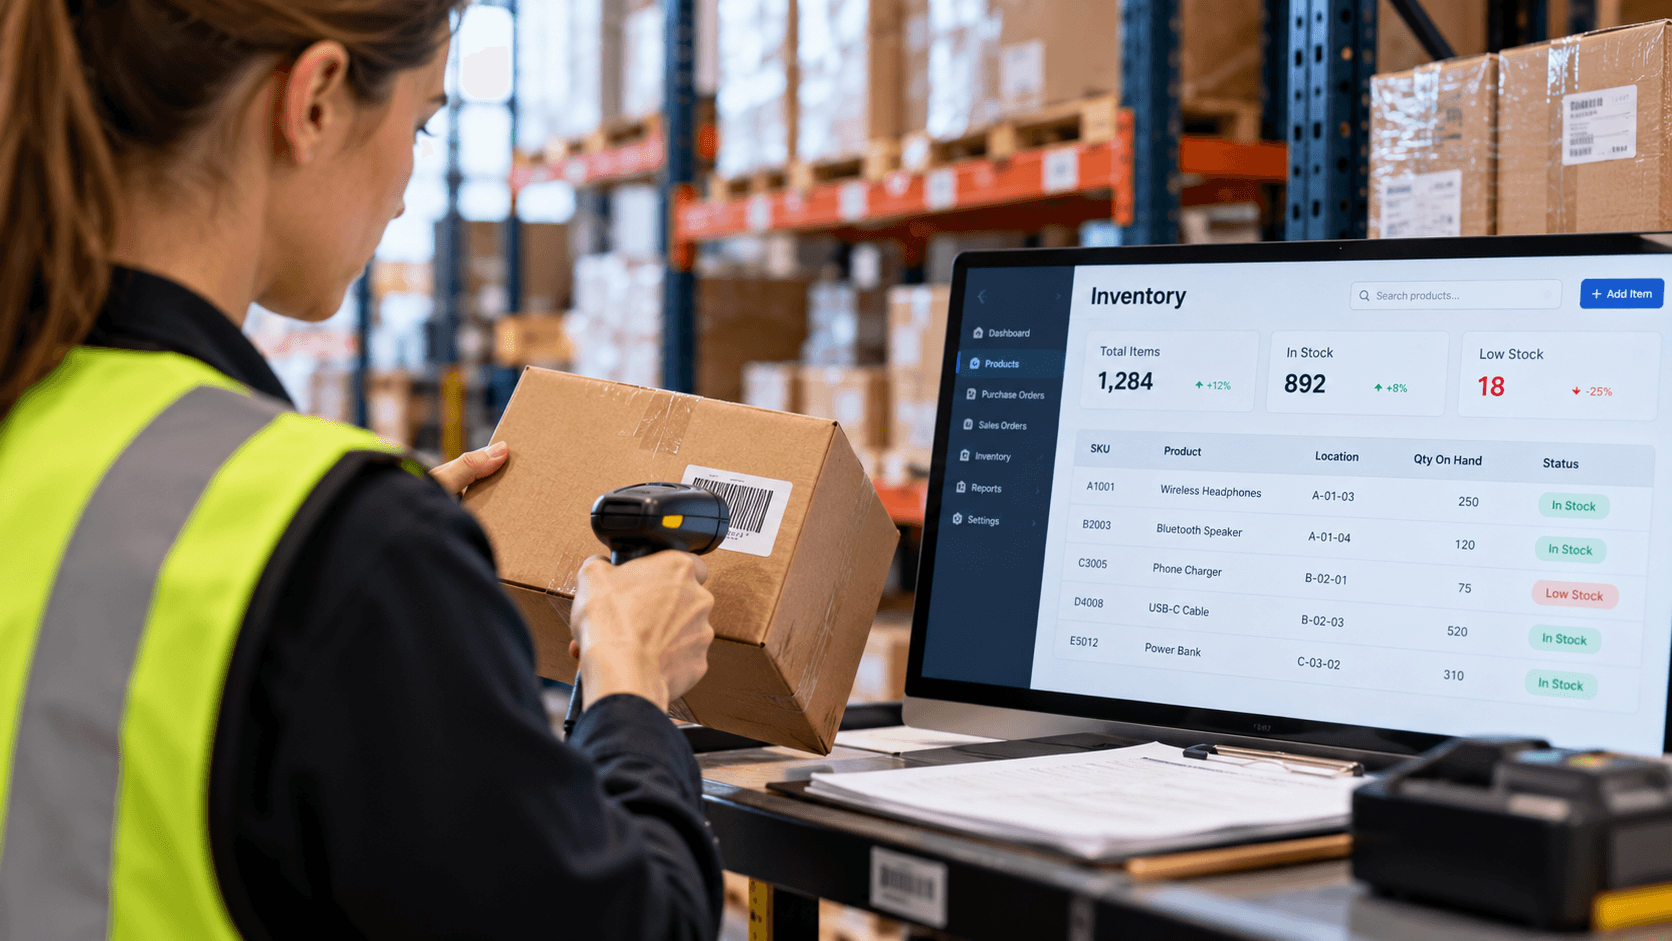
Perpetual inventory is an inventory recordkeeping system that continuously updates inventory balances as purchases, sales, returns, and other stock movements are recorded. Instead of waiting until the end of an accounting period to calculate inventory from a physical count, a perpetual inventory system maintains an ongoing record of available quantities and, when properly configured, inventory values and cost of goods sold.
Understanding perpetual inventory is important for wholesale distributors because thousands of products can move through receiving docks, warehouse shelves, customer orders, and returns every day. A company that relies only on occasional inventory counts may struggle to determine which items are available for sale. Inaccurate stock records can cause backorders, emergency purchases, incorrect customer promises, and unreliable financial reporting.
A perpetual inventory system can improve visibility, but it does not automatically guarantee accuracy. Every physical movement must be captured correctly, and businesses still need cycle counts and reconciliation procedures. The value of the system depends on consistent processes, reliable item data, and integration between warehouse operations, purchasing, sales, and accounting.
What Is Perpetual Inventory?
Perpetual inventory is a method of maintaining continuously updated records of inventory quantities and related values as transactions occur. Each properly recorded receipt increases inventory, while each shipment or other authorized issue reduces it. Returns, adjustments, transfers, and write-offs also change the recorded balance.
For example, a distributor begins the day with 500 units of a replacement part. The warehouse receives 200 additional units, ships 120 units to customers, and records five damaged units as unavailable. Assuming all transactions are posted correctly, the recorded on-hand quantity becomes 575 units.
This record can help sales personnel identify what is available and assist purchasing teams in planning replenishment. However, on-hand inventory is not necessarily the same as available-to-promise inventory. Customer allocations, reservations, quality holds, and other restrictions must also be considered when determining what can be sold.
Perpetual Inventory Meaning in Simple Terms
Perpetual inventory means the business updates its stock records whenever inventory changes instead of relying solely on periodic stock counts. When 20 units arrive, the system records the receipt. When eight units ship, the system records the reduction.
The process provides a running inventory balance that can be consulted by warehouse, purchasing, and customer-service employees. Businesses can use barcode scanners, warehouse management systems, ERP platforms, or other tools to support those transactions. The system remains accurate only when physical events and recorded transactions match.
How Does a Perpetual Inventory System Work?
A perpetual inventory system works by recording stock movements and updating item balances whenever relevant transactions are processed. Each transaction has a reason, quantity, product identifier, location, and other information required by the business. The updated balance becomes the starting point for the next transaction.
A typical wholesale distribution process begins when products are received from suppliers. Warehouse personnel verify the shipment, capture accepted quantities, and record the products in the system. Customer shipments then reduce the stock balance, while returns, transfers, and adjustments create additional transactions.
The main steps include:
- Create accurate SKU and unit-of-measure records.
- Record inventory receipts after checking deliveries.
- Assign received goods to warehouse locations.
- Reserve or allocate inventory to customer orders.
- Confirm picking and shipping transactions.
- Record customer and supplier returns.
- Process authorized transfers and inventory adjustments.
- Reconcile records with periodic physical verification.
The system may also connect with purchasing, accounting, transportation, and forecasting tools. Integration reduces the need for employees to enter the same information into multiple applications. The Inventory Management for Distribution guide explains how inventory accuracy interacts with working capital and customer service.
Perpetual Inventory Example With Calculations
A perpetual inventory example shows how stock balances change after each recorded purchase, shipment, return, or adjustment. Consider a distributor that sells standardized industrial fittings. The company tracks each transaction in its inventory system.
The final recorded on-hand quantity is 400 units. If warehouse staff later count only 396 units, the business must investigate a four-unit discrepancy. Possible explanations include picking errors, unrecorded damages, mislocated stock, or incorrect transaction quantities.
A perpetual system makes discrepancies easier to investigate because every transaction is associated with a record. It does not guarantee that the reason for a discrepancy will be obvious. Accurate timestamps, user information, document references, and location tracking improve the quality of investigations.
| Transaction | Units received | Units issued | Recorded on-hand balance |
|---|---|---|---|
| Opening inventory | — | — | 400 |
| Supplier receipt | 250 | — | 650 |
| Customer shipment | — | 180 | 470 |
| Customer shipment | — | 75 | 395 |
| Saleable customer return | 10 | — | 405 |
| Damaged stock adjustment | — | 5 | 400 |
Perpetual Inventory vs. Periodic Inventory
The main difference between perpetual and periodic inventory is when inventory records and accounting balances are updated. Perpetual inventory updates relevant records continuously as transactions are posted, while periodic inventory determines ending inventory and cost of goods sold through adjustments at defined intervals. Both methods require accurate physical information.
A small business with only a few low-volume products may be able to operate with a simpler periodic method. A high-volume distributor with many SKUs, multiple warehouses, and daily order fulfillment typically benefits from more timely stock visibility. The best choice depends on operating complexity and financial reporting requirements.
Periodic Inventory Example
Under a periodic inventory system, cost of goods sold is commonly calculated from beginning inventory, purchases, and ending inventory, with relevant adjustments.
COGS = Beginning inventory + Net purchases − Ending inventory
Assume beginning inventory is valued at $40,000, net purchases total $90,000, and ending inventory is valued at $35,000.
COGS = $40,000 + $90,000 − $35,000
COGS = $95,000
The calculation establishes the cost of merchandise sold for the period, assuming the inputs are properly measured and adjusted. A perpetual inventory system instead records cost movements throughout the period, subject to reconciliation and the company's accounting policies.
| Feature | Perpetual inventory | Periodic inventory |
|---|---|---|
| Inventory updates | As transactions are recorded | At reporting or counting intervals |
| Visibility | Running stock balance | May rely on separate operational records |
| COGS accounting | Updated as sales are recorded | Calculated at period end |
| Technology | Often supported by integrated systems | Can be managed with simpler records |
| Physical counts | Still required for verification | Required to establish ending inventory |
| Error identification | Potentially more timely | Often delayed until reconciliation |
| Operational complexity | Higher process and data requirements | Simpler accounting mechanics |
How Does Perpetual Inventory Track Cost of Goods Sold?
Perpetual inventory can update cost of goods sold as inventory is sold by applying the company's selected inventory cost-flow method. A system may use FIFO, moving weighted average, specific identification, or another appropriate method depending on the inventory and applicable accounting framework. The operational movement of a particular product does not necessarily equal the accounting cost flow used.
Suppose a distributor buys 100 units at $10 each and later purchases another 100 units at $12 each. The company then sells 120 units. The reported cost of goods sold depends on the valuation method.
Perpetual FIFO Example
Under first-in, first-out accounting, the oldest costs are assigned to sales first.
COGS = (100 × $10) + (20 × $12)
COGS = $1,240
The remaining 80 units are valued at $12 each, producing ending inventory of $960. Total inventory costs available were $2,200, so the sum of COGS and ending inventory reconciles to that amount.
Moving Weighted Average Example
Under a perpetual moving weighted-average method, the average unit cost is recalculated after applicable new purchases. Before the sale, the company holds 200 units with a total cost of $2,200.
Average unit cost = $2,200 ÷ 200 = $11
COGS = 120 × $11 = $1,320
Ending inventory = 80 × $11 = $880
These results are based on an intentionally simple example in which both purchases precede the sale. The timing of receipts matters in moving-average systems, and real inventory accounting can include freight, discounts, returns, write-downs, and other adjustments.
| Metric | Perpetual FIFO | Moving weighted average |
|---|---|---|
| Units sold | 120 | 120 |
| COGS | $1,240 | $1,320 |
| Units remaining | 80 | 80 |
| Ending inventory value | $960 | $880 |
| Total costs accounted for | $2,200 | $2,200 |
Perpetual Inventory vs. FIFO
Perpetual inventory describes when records are updated, while FIFO describes how inventory costs are assigned to goods sold and ending inventory. These are separate concepts. A business can operate a perpetual inventory system using FIFO or another permitted valuation method.
The distinction is important because operational staff often use FIFO to describe physically picking the oldest merchandise first. Accounting FIFO concerns assigning the oldest available inventory costs to sales, which may not always match the physical item selected. Perishable or date-sensitive products may instead use physical first-expired, first-out procedures to reduce spoilage.
A distributor should document both its warehouse picking rules and accounting valuation policy. Clear distinctions reduce confusion when physical inventory and accounting reports are compared. Appropriate systems can support these different requirements simultaneously.
Benefits of Perpetual Inventory
Perpetual inventory can improve stock visibility, replenishment decisions, order accuracy, and financial information when transactions are recorded consistently. Its main operational advantage is providing an updated record that employees can consult without waiting for a complete stock count. This can be valuable when hundreds of orders are processed daily.
Better Product Availability
Current stock records help customer-service teams determine whether a product can be supplied. The system can identify received quantities, committed orders, and inventory restrictions if the underlying processes capture them correctly. This reduces the chance of promising goods that are not available.
Availability must still be distinguished from inventory quantity. A distributor may have 100 units physically present while 80 are already reserved for existing orders. The accurate available-to-promise quantity may therefore be substantially lower.
Faster Replenishment Decisions
Purchasing teams can use updated inventory positions to identify products approaching reorder points. Automated alerts may reduce dependence on manual spreadsheet reviews. The quality of these decisions still depends on demand forecasts, supplier lead times, and inventory policy settings.
A perpetual system is especially useful when sales volume changes rapidly. It allows buyers to compare current stock positions with open purchase orders and committed customer demand. Poorly configured reorder levels, however, can still create excess purchasing.
Improved Inventory Accountability
Detailed transaction histories can help managers investigate discrepancies and identify recurring operational errors. Each receipt, adjustment, return, and shipment should have an authorized reason and document reference. This creates a clearer audit trail than relying exclusively on occasional counts.
Regular review can reveal problems such as incorrect units of measure, duplicate receipts, unrecorded damages, and repeated picking errors. Fixing the underlying process is more valuable than repeatedly adjusting inventory balances to match physical stock.
More Timely Financial Information
A perpetual accounting system can provide updated inventory values and cost of goods sold during the reporting period. This helps management monitor gross margin without waiting for a full physical inventory. Nevertheless, financial statements still require appropriate reconciliations, valuation reviews, and accounting controls.
Businesses should not assume every operational transaction automatically creates correct financial information. Incorrect product costs, returns, and inventory adjustments can affect reported margins. Accounting oversight remains essential.
Disadvantages of Perpetual Inventory
Perpetual inventory requires reliable data capture, employee training, transaction controls, and ongoing reconciliation. Software alone cannot prevent stock discrepancies. Businesses with inconsistent receiving or shipping processes may create inaccurate records faster than they can correct them.
Implementation costs can include software subscriptions or licenses, integration work, scanners, labels, staff training, and process redesign. Larger operations may also require location-level inventory tracking, serial numbers, lot records, or multiple units of measure. These requirements should be evaluated before choosing a system.
Another limitation is the risk of false confidence. If employees believe the system is always correct, they may overlook physical discrepancies or unauthorized stock movements. Management should use perpetual records as a continuously updated estimate supported by verification rather than as an unquestionable replacement for physical controls.
Perpetual Inventory and Barcode Scanning
Barcode scanning supports perpetual inventory by connecting physical movements with electronic transactions. Employees can scan product identifiers and locations during receiving, picking, transfers, and counting. This reduces some manual-entry errors and helps standardize warehouse procedures.
A successful barcode workflow requires correct item labeling, consistent packaging units, and clear scan requirements. For example, scanning a case barcode while the system expects individual units can create major quantity errors. Master data must accurately define how cases, packs, and pieces relate to each other.
Scanning can also support traceability when systems capture lot or serial identifiers. Businesses handling regulated products or goods subject to recalls may require more detailed controls. Barcode technology is useful only when the system records the correct business event.
Perpetual Inventory and Warehouse Management Systems
A warehouse management system can improve perpetual inventory by recording stock movements at the location and task level. ERP systems may maintain financial inventory records, while WMS platforms support physical activities such as putaway, picking, replenishment, and cycle counting. Integrated systems must agree on transaction timing and ownership.
A distributor operating several warehouses may need to track product availability by facility, aisle, bin, lot, or status. Location accuracy becomes especially important when the same SKU is stored in several areas. A system that shows the correct total quantity but the wrong location can still cause missed orders and excess handling.
Warehouse software should support exception management, not merely transaction capture. Damaged goods, shortages, substitutions, and partial receipts need defined workflows. The Order Fulfillment Process explains how warehouse events connect with customer delivery obligations.
Perpetual Inventory and Cycle Counting
Cycle counting is the periodic verification of selected stock quantities without shutting down the entire warehouse for a complete count. It is an important control in a perpetual inventory environment because electronic balances can differ from actual stock. Regular counts help identify and correct these differences.
Businesses may count high-value or high-velocity items more frequently than low-priority products. They can also prioritize SKUs with recent discrepancies, repeated returns, or operational complexity. Count frequency should reflect risk, not only product value.
Example of a Cycle Count Discrepancy
Assume the perpetual system shows 250 units of a product, but the physical count identifies 244. The six-unit discrepancy should be investigated before approving an adjustment.
Simply changing the balance to 244 may correct the immediate record but leave the underlying process unchanged. A recurring discrepancy indicates that the organization needs to improve transaction controls. Inventory accuracy should be monitored alongside count results and adjustment reasons.
| Investigation step | Question |
|---|---|
| Check recent receipts | Was a delivery recorded incorrectly? |
| Review shipments | Did an order ship without a completed transaction? |
| Search nearby locations | Were units put away in the wrong bin? |
| Review damages | Were damaged goods removed physically but not electronically? |
| Check unit conversions | Was a case recorded as individual pieces? |
| Authorize correction | Who approves the final stock adjustment? |
How to Implement a Perpetual Inventory System
Implementing perpetual inventory requires clean product data, documented movement processes, appropriate software, and routine reconciliation. The first objective is to establish a reliable physical-to-digital transaction process. Automating inconsistent warehouse procedures without correcting them can make errors harder to identify.
Step 1: Standardize Product Records
Create a unique SKU for each relevant product or variation and define its units of measure. Confirm barcodes, product descriptions, packaging quantities, and storage requirements. Duplicate or inconsistent master records should be corrected before implementation.
Step 2: Map Inventory Transactions
Document every physical event that changes inventory quantity, location, or status. This includes receipts, transfers, shipments, customer returns, supplier returns, damage, and authorized adjustments. Assign responsibility for recording each event.
Step 3: Choose Appropriate Technology
Select software that supports the company's actual transaction volume, warehouse complexity, and accounting requirements. Evaluate integration with sales orders, purchasing, finance, and shipping systems. The most expensive platform is not automatically the best fit.
Step 4: Establish Opening Balances
Perform a reliable count and reconcile the initial inventory quantities and values before moving to the new system. Incorrect starting balances will undermine later transaction accuracy. Validate representative products and locations before completing the transition.
Step 5: Train Employees and Test Workflows
Employees should understand when to scan, record, or approve each transaction. Test normal receipts and shipments as well as damaged products, partial deliveries, and returns. Exceptions are often where inventory records become unreliable.
Step 6: Monitor Accuracy
Use cycle counts, exception reports, inventory adjustments, and reconciliation procedures to evaluate performance. Track recurring errors rather than only final count differences. Continuous improvement should become part of warehouse supervision.
Perpetual Inventory KPIs for Distributors
Perpetual inventory performance should be evaluated using inventory accuracy, stock availability, turnover, shrinkage, and transaction quality. These metrics reveal whether ongoing records actually support operational decisions. A system can process many transactions while still producing poor inventory information.
Metrics should use consistent definitions across locations. For example, one warehouse may count any discrepancy as an inventory error while another counts only discrepancies above a financial threshold. Standard measurement allows management to identify meaningful differences.
| KPI | What it measures | Why it matters |
|---|---|---|
| Inventory record accuracy | Agreement between system and physical counts | Reliability of inventory data |
| Inventory turnover | Rate at which inventory is sold and replaced | Capital efficiency |
| Stockout rate | Frequency of unavailable products | Customer-service exposure |
| Order fill rate | Portion of demand filled from available inventory | Service performance |
| Shrinkage | Inventory losses not explained by normal sales | Operational control |
| Adjustment frequency | Number or value of manual stock corrections | Process stability |
| Cycle count completion | Execution of planned stock verification | Control discipline |
Final Takeaway
Perpetual inventory provides continuously updated inventory records that support purchasing, fulfillment, and financial decisions. Its advantage is better visibility into stock movement rather than complete elimination of physical counts or operational errors. Accurate results depend on clear warehouse processes, reliable item records, and timely transactions.
Wholesale distributors should treat perpetual inventory as a management system supported by people, software, and verification controls. When implemented well, it can reduce stock discrepancies and improve order reliability. When implemented poorly, it can create misleading balances that disrupt the entire supply
Frequently Asked Questions
- What is perpetual inventory in simple terms?
- Perpetual inventory is a method of updating stock records whenever products are received, sold, returned, transferred, or adjusted. It provides an ongoing view of recorded quantities. Physical verification is still necessary.
- What is an example of a perpetual inventory system?
- A wholesaler using barcode scanners to record receipts and customer shipments operates a perpetual inventory process when those transactions continuously update inventory records. The system may also update inventory costs and cost of goods sold. Accurate operation depends on correctly recording physical movements.
- What is the difference between periodic and perpetual inventory?
- Periodic inventory determines inventory and cost of goods sold at reporting intervals, while perpetual inventory updates relevant records as transactions occur. Perpetual systems provide more timely information but require stronger transaction controls.
- Does perpetual inventory eliminate physical inventory counts?
- No. Physical counts and cycle counting remain important because unrecorded damage, theft, picking errors, and incorrect transactions can cause discrepancies. Electronic records should be regularly checked against actual stock.
- Is perpetual inventory the same as FIFO?
- No. Perpetual inventory determines when inventory records are updated. FIFO is an inventory cost-flow method that can be used within a perpetual or periodic accounting system.
- Is perpetual inventory good for small businesses?
- It can be, especially when the business manages many SKUs or frequent orders. However, implementation costs and process requirements should be appropriate for the operation. Even a simple system needs reliable data capture and reconciliation.