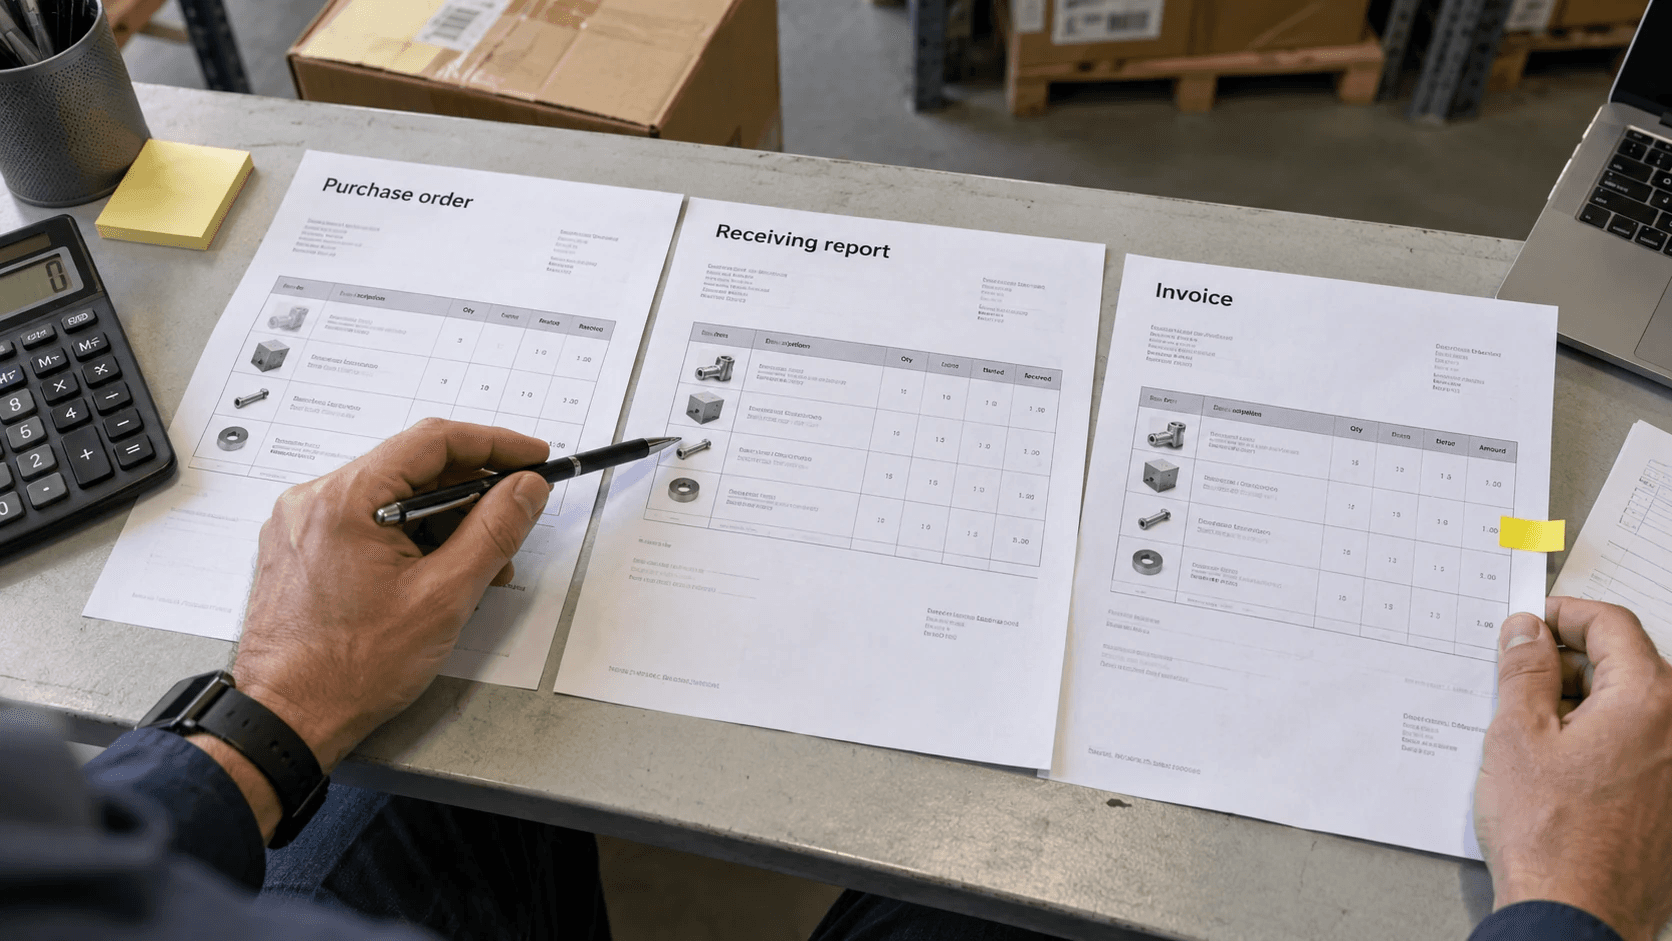
Three-way matching in accounts payable compares a supplier invoice with the approved purchase order and the record of goods received. The purchase order establishes what the business authorized, the receipt records what arrived, and the invoice states what the supplier wants paid. Payment approval follows the company’s matching rules, tolerances, and exception procedures.
The control is especially useful when deliveries are partial, quantities change, or different employees handle buying and receiving. An invoice may reproduce the original order perfectly while billing for units that are still in transit. A receiving check adds evidence that the ordered quantity actually reached the business.
How Does Three-Way Matching Work?
Three-way matching works by connecting authorization, receipt, and billing at the relevant purchase-order line. Microsoft’s invoice-matching documentation distinguishes price checks against the purchase order from quantity checks against the matched product receipt. A discrepancy can be evaluated against configured tolerances rather than treated as an automatic approval.
The three records do not need to be paper documents. A digital purchase order, a warehouse receipt, and an electronic supplier invoice can serve the same purpose. What matters is a dependable link between the transaction records and a clear history of changes.
The records answer different business questions, as the following comparison shows.
Agreement across the records supports approval, but it is not proof that every risk has been eliminated. A false receipt or an unauthorized change to supplier details can defeat an otherwise tidy match. Three-way matching belongs within a broader payment-control process.
| Record | Main question | Information to verify |
|---|---|---|
| Purchase order | What did the business authorize? | Supplier, item, quantity, price, terms |
| Receiving record | What did the business receive? | Item, quantity, receipt date, receipt reference |
| Supplier invoice | What is being billed? | Invoice number, item, quantity, price, charges |
Three-Way Matching Example: A Partial Delivery
A three-way matching example reveals its value when the supplier bills more than the warehouse has received. Consider a hypothetical distributor ordering 100 units at $20 each. The supplier delivers 80 units but sends an invoice for the full 100-unit order.
The price is correct and the invoice matches the original purchase order. The receipt, however, supports only the delivered quantity.
Under a receipt-based policy with no permitted overbilling, the $400 difference should be investigated before approval. The remaining 20 units might be scheduled for a later delivery, missing from the receipt record, or incorrectly billed. Each possibility requires a different correction.
The buyer should confirm the commercial position while receiving verifies the physical count. Accounts payable should then follow the agreed method for a corrected invoice, a credit, or an authorized partial payment. Editing the receipt to make the invoice pass would remove the evidence needed to resolve the problem.
| Field | Purchase order | Receiving record | Supplier invoice |
|---|---|---|---|
| Quantity | 100 | 80 | 100 |
| Unit price | $20 | Not applicable | $20 |
| Goods value | $2,000 | $1,600 at PO price | $2,000 |
| Initial result | Authorized order | Partial delivery | 20 units require resolution |
What Is the Difference Between Two-, Three-, and Four-Way Matching?
Two-way matching compares the order and invoice, three-way matching adds receipt evidence, and four-way matching adds inspection acceptance. Oracle’s procurement documentation separates these approval levels and describes matching within defined tolerances. The appropriate level depends on what evidence the organization requires before payment.
A routine service subscription may not have a warehouse receipt, while a purchase of physical stock usually does. A product requiring quality inspection may need an additional acceptance record. Applying the same workflow to every spending category can create either unnecessary administration or insufficient control.
The comparison below illustrates how the evidence changes.
The names describe control logic rather than a guarantee that every software platform behaves identically. Matching configuration, status rules, and payment holds still require review. A company should test its actual workflow using realistic cases before relying on automatic approval.
| Method | Evidence compared | Typical control purpose |
|---|---|---|
| Two-way | Purchase order and invoice | Check billing against authorization |
| Three-way | Purchase order, receipt, and invoice | Check that billed goods were received |
| Four-way | Purchase order, receipt, acceptance, and invoice | Check that received goods also passed acceptance |
How to Set Up a Three-Way Matching Process
A three-way matching process needs reliable purchase orders, timely receiving records, and a defined exception owner. Accounts payable cannot reconstruct those inputs accurately after an invoice arrives. The workflow should therefore begin with purchasing and receiving rather than with the payment run.
For a small business, the first implementation can be simple. A controlled register may link approved orders, receiving references, and invoices while the team establishes consistent habits. However, shared access should not allow employees to overwrite evidence without a record.
A practical setup follows this sequence.
- Define which purchases require a purchase order.
- Standardize supplier, item, and unit-of-measure records.
- Record actual receipts against the correct order lines.
- Capture invoice numbers, quantities, prices, and charges.
- Apply matching rules and route discrepancies.
- Record approval and retain the supporting evidence.
The main outcome is a repeatable decision trail. A reviewer should be able to see why an invoice passed, why an exception was approved, and which receipt supported payment. That trail is more valuable than a spreadsheet cell marked “checked.”
Who Should Resolve Matching Exceptions?
Matching exceptions should go to the person who can verify the disputed fact. Purchasing should confirm agreed prices and approved order changes, while receiving should confirm counts and delivery details. Accounts payable should coordinate the records and payment status without inventing missing operational evidence.
In a very small company, one employee may perform several roles. Management can still introduce a second review for unusual suppliers, changed payment instructions, or material exceptions. The objective is to reduce opportunities for one person to create, receive, and pay an unsupported purchase without scrutiny.
Exception ownership should also include a response deadline. A correct invoice left unresolved can still become overdue. Delayed receiving records are an operating problem, not a reason to bypass the control repeatedly.
How Matching Tolerances Should Be Used
Matching tolerances define which differences may pass automatically and which require review. Microsoft documents separate controls for unit prices, line totals, and other matching information. The software’s capability should not be confused with a recommendation for any particular percentage.
Suppose a hypothetical business permits a price difference of up to $5 per invoice line and 1% of the authorized line value, requiring both limits to be satisfied. A $12 difference would fail even if it represented less than 1% of a large order. Using both controls limits the exposure that a percentage-only rule might permit.
Tolerance decisions should reflect transaction risk and correction cost. A small rounding difference is different from an extra carton of expensive inventory. Repeated small variances also deserve attention because an acceptable individual difference can become material across many invoices.
What Happens With Multiple Receipts and Invoices?
Three-way matching must consider cumulative quantities when one order produces several receipts or invoices. A purchase order for 100 units may be delivered in two batches and billed in two installments. The matching process should track what has already been received, invoiced, credited, and approved.
Suppose the first receipt records 60 units and the first invoice bills 60. A second receipt records the remaining 40, but a later invoice mistakenly bills 50. Comparing the second invoice only with the original 100-unit order can miss the overbilling.
The control needs an accurate remaining balance. Previously invoiced quantities must not become available for approval again merely because a new document has a different invoice number. Returns and credits should also update the relevant transaction history.
Reliable perpetual inventory records support this process by preserving stock movements. The inventory record still needs valid receipt evidence behind it. A quantity entered only to satisfy an invoice match weakens both inventory accuracy and payment control.
What Three-Way Matching Does Not Prove
Three-way matching does not automatically verify product quality, supplier bank details, or invoice uniqueness. A delivery can be physically received but fail inspection later. Duplicate invoices can also carry valid order and receipt information unless the payment workflow checks for duplication separately.
Oracle’s distinction between receipt and inspection acceptance is important here. Four-way approval adds acceptance evidence where that control is required. A three-way match should not be described as a quality guarantee.
Likewise, a proforma invoice serves a different purpose from the final commercial invoice used in the payment workflow. Teams should identify document type before routing it for approval. A preliminary document should not accidentally create a second payable obligation.
When Does Automation Make Sense?
Automating three-way matching makes sense when transaction volume or exception complexity exceeds what a controlled manual workflow can handle reliably. The business should first identify which errors consume time. Automating inconsistent item codes and late receiving records can accelerate confusion rather than reduce it.
A software evaluation should test partial receipts, duplicate invoices, credits, price changes, and transactions with several units of measure. Reviewers should also inspect user permissions and the evidence retained after an override. A demonstration containing only perfectly matched invoices does not show how the system handles real operating conditions.
The broader comparison of distribution management software can help identify where purchasing, inventory, and finance connect. The matching decision should remain tied to measurable needs. Fewer unsupported payments, shorter exception queues, and clearer accountability are more useful objectives than automation alone.
Frequently Asked Questions
- Is three-way matching legally required for every business?
- Three-way matching is a payment-control method, not a universal legal requirement for every U.S. purchase. Specific organizational, contractual, or regulatory obligations may impose additional controls. Businesses should define their policy according to their circumstances.
- Can three-way matching be used for services?
- Services can use documented confirmation that the agreed work was performed. That evidence might be a milestone approval or service-entry record rather than a warehouse receipt. The workflow must make the accepted scope and approver clear.
- What if an invoice arrives before the goods?
- The invoice can be recorded according to the company’s accounting workflow while payment approval remains subject to the required evidence. An advance-payment arrangement needs its own authorized process. Employees should not create a fictional receipt to release it.
- Can a small business perform three-way matching without an ERP?
- A small business can use a controlled register and linked supporting documents. Access, version history, remaining quantities, and approval evidence still matter. As transaction complexity grows, the limitations of manual tracking become more significant.