Growth
Markup vs Margin: Formulas, Examples, and Calculator
A 40% markup is not a 40% profit margin. Discover the difference between markup and margin, calculate both correctly, and see how pricing mistakes affect wholesale and retail businesses.
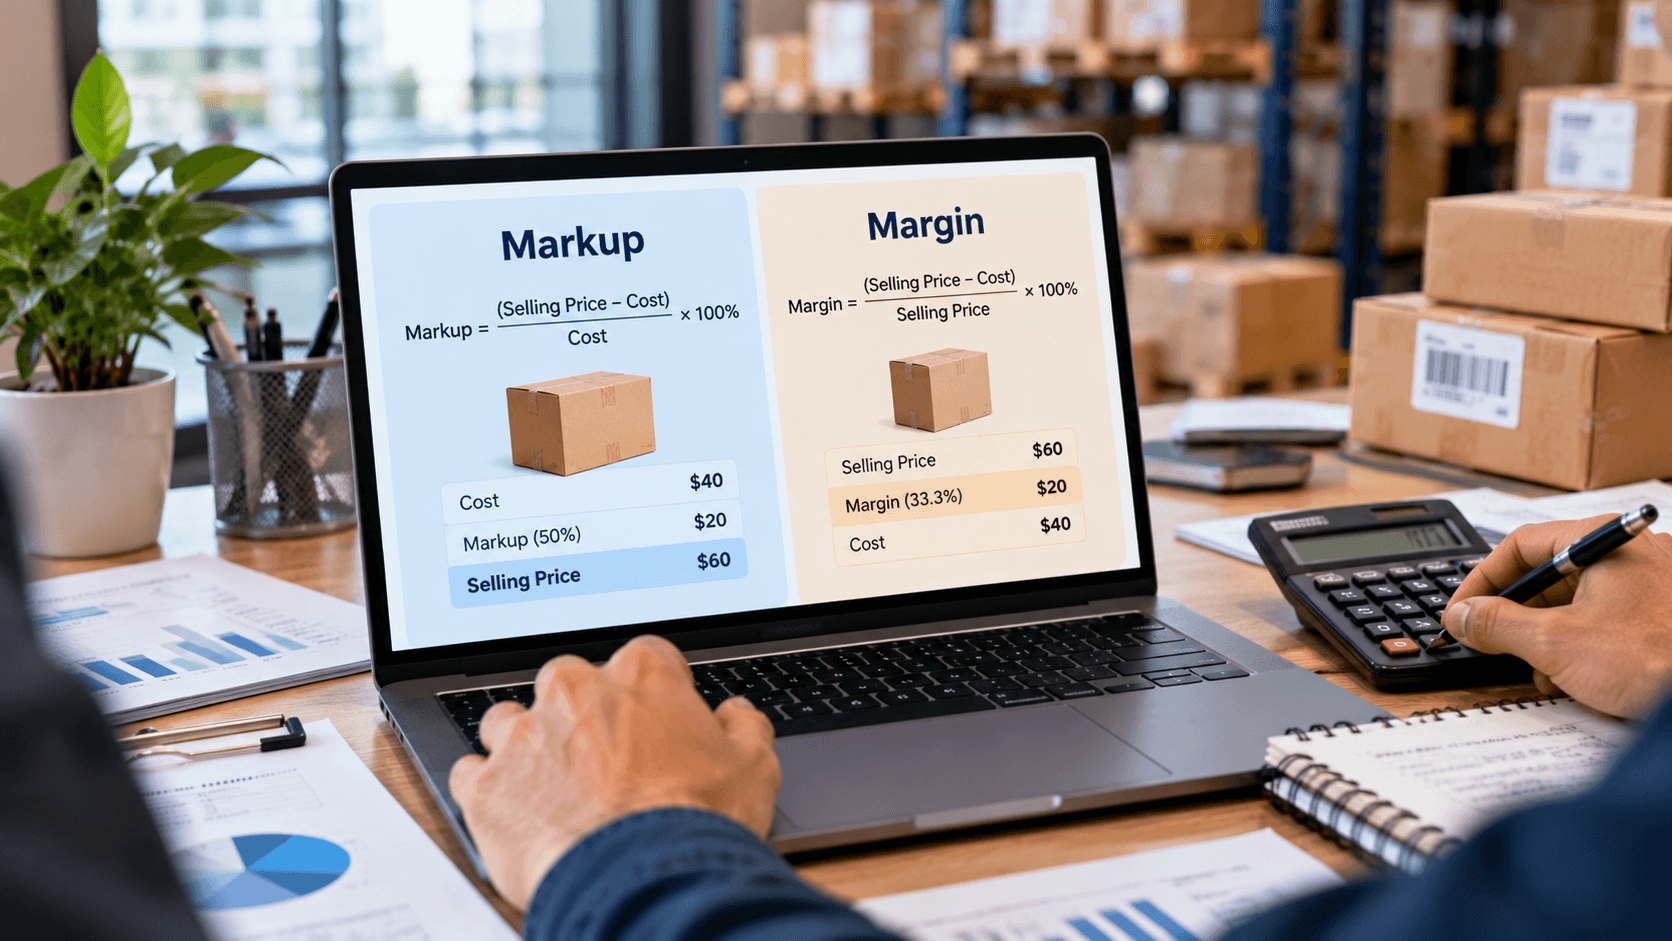
Markup vs margin is the difference between measuring profit against product cost and measuring profit against selling price. Markup expresses gross profit as a percentage of cost, while gross margin expresses gross profit as a percentage of revenue. The two percentages are not interchangeable, even when they describe the same product and transaction.
Understanding markup vs margin is essential for business owners, retailers, wholesalers, and distributors who set product prices. A business targeting a 40% gross margin but using a 40% markup will charge less than intended. Repeating that mistake across hundreds of products can substantially reduce gross profit and leave insufficient revenue to cover operating expenses.
The distinction becomes particularly important in wholesale distribution, where customer discounts, freight, credit terms, and inventory costs already create pressure on profitability. Accurate pricing requires a consistent cost definition, the correct calculation, and ongoing monitoring of actual selling prices.
What Is the Difference Between Markup and Margin?
The main markup vs margin difference is the denominator used in the calculation. Markup compares gross profit with cost, whereas gross margin compares gross profit with selling revenue. Both calculations use the same dollar difference between selling price and cost, but they express it differently.
Consider a product purchased for $60 and sold for $100. Its gross profit is $40, excluding any additional adjustments to cost or revenue. The markup is 66.67% because the $40 difference is compared with the $60 cost, while the gross margin is 40% because that difference is compared with the $100 selling price.
Both measurements are useful. Problems occur when sales teams, business owners, or software systems use the word margin while applying a markup calculation.
| Metric | Markup | Gross margin |
| Measures profit relative to | Product cost | Selling price |
| Formula | Gross profit ÷ Cost × 100 | Gross profit ÷ Revenue × 100 |
| Example | $40 ÷ $60 = 66.67% | $40 ÷ $100 = 40% |
| Common application | Cost-plus pricing | Financial analysis and margin targets |
| Can exceed 100%? | Yes | Not for a positive-cost, positive-revenue sale |
Markup Formula: How to Calculate Markup
The markup formula divides the difference between selling price and cost by the product's cost. It shows how much has been added above cost when establishing the selling price. Markup is frequently used in cost-plus pricing because it begins with an amount the business already knows.
Markup (%) = (Selling price − Cost) ÷ Cost × 100
Suppose a wholesaler purchases a product for $25 and sells it to a retailer for $35.
Markup = ($35 − $25) ÷ $25 × 100
Markup = 40%
The company has added $10 to a $25 cost. However, the gross margin is only approximately 28.57%, because $10 divided by the $35 selling price is different from $10 divided by cost.
Selling Price From Markup
Selling price from markup is calculated by multiplying cost by one plus the markup rate. This calculation works when cost is defined correctly and the desired markup is expressed as a decimal.
Selling price = Cost × (1 + Markup rate)
For a product costing $80 with a 35% markup:
$80 × 1.35 = $108
The resulting gross profit is $28, and gross margin is approximately 25.93%. This demonstrates why businesses should not interpret a 35% markup as a 35% gross margin.
Margin Formula: How to Calculate Gross Margin
The gross margin formula divides gross profit by net sales revenue and expresses the result as a percentage. It measures how much of each revenue dollar remains after cost of goods sold. Those remaining dollars must cover operating expenses and contribute to eventual profit.
Gross margin (%) = (Revenue − COGS) ÷ Revenue × 100
Imagine a distributor sells an item for $150 and its recognized cost of goods sold is $105.
Gross profit = $150 − $105 = $45.
Gross margin = $45 ÷ $150 × 100 = 30%.
The distributor has $45 in gross profit to contribute toward outbound fulfillment, administration, sales expenses, and other costs not included in COGS. A 30% gross margin is not the same as a 30% net profit margin.
Selling Price From Target Margin
To calculate a selling price from target gross margin, divide cost by one minus the desired gross margin. This formula is particularly useful when management sets minimum gross-margin requirements.
Selling price = Cost ÷ (1 − Target gross margin)
Suppose a product costs $80 and the target gross margin is 35%.
$80 ÷ 0.65 = $123.08
At this selling price, the gross profit is approximately $43.08. Comparing that with the earlier 35% markup example shows a $15.08 difference in selling price on the same product.
Markup vs Margin Conversion Table
A markup vs margin conversion table shows how the two percentages relate when product cost and selling price are held constant. Margin will be lower than markup for a transaction with positive cost and gross profit.
The table explains why applying a 30% cost markup does not produce a 30% gross margin. At a 30% markup, approximately 23.08% of revenue remains as gross profit.
Convert Markup to Margin
Markup converts to margin by dividing the markup rate by one plus the markup rate.
Gross margin = Markup ÷ (1 + Markup)
For a 50% markup:
0.50 ÷ 1.50 = 0.3333, or 33.33%.
Convert Margin to Markup
Margin converts to markup by dividing the margin rate by one minus the margin rate.
Markup = Gross margin ÷ (1 − Gross margin)
For a 40% gross margin:
0.40 ÷ 0.60 = 0.6667, or 66.67%.
These conversions require percentages to be represented as decimals during the calculation.
| Markup | Equivalent gross margin |
| 10% | 9.09% |
| 15% | 13.04% |
| 20% | 16.67% |
| 25% | 20.00% |
| 30% | 23.08% |
| 40% | 28.57% |
| 50% | 33.33% |
| 60% | 37.50% |
| 75% | 42.86% |
| 100% | 50.00% |
Markup vs Margin Calculator: Worked Example
A markup vs margin calculator needs product cost and selling price to determine gross profit, markup percentage, and gross margin percentage. If the objective is to find a target selling price, it can instead use cost and a desired markup or margin.
Consider a wholesale business with these inputs:
The $27 gross profit is divided by $48 to calculate markup, and by $75 to calculate gross margin. A useful calculator should also display the selling price required for a different target margin. For example, reaching a 40% gross margin with the same $48 cost requires a price of $80.
The cost input must represent the appropriate amount for the transaction. In wholesale distribution, supplier invoice price alone may not include inbound freight, import charges, or other expenses included in the inventory's recognized cost.
| Calculator input | Value |
| Product cost | $48 |
| Selling price | $75 |
| Gross profit | $27 |
| Markup | 56.25% |
| Gross margin | 36.00% |
Why Markup vs Margin Matters in Wholesale Distribution
Markup vs margin errors can materially affect wholesale distributors because a seemingly small pricing discrepancy multiplies across large order volumes. A distributor may sell thousands of units monthly while operating with meaningful freight, warehouse, credit, and inventory costs. Setting prices below the intended margin can produce strong revenue but weak financial returns.
Suppose a company purchases 10,000 units at $20 each and intends to achieve a 30% gross margin. If it accidentally uses a 30% markup, it sets the price at $26. The correct price for a 30% margin would be approximately $28.57.
The difference is approximately $25,700 in gross profit on those 10,000 units, assuming all units sell at the indicated prices. The example does not assume that the market will necessarily accept the higher price. It demonstrates the financial consequence of confusing the intended pricing formula.
Businesses should also consider customer-specific costs. An account requiring frequent small deliveries and extended payment terms can have a lower contribution than one purchasing full pallets and paying promptly. The guide to Pricing and Profit Margins in Distribution explains why landed cost and cost-to-serve belong in distributor pricing decisions.
| Metric | 30% markup pricing | 30% margin pricing |
| Cost per unit | $20 | $20 |
| Selling price per unit | $26 | $28.57 |
| Gross profit per unit | $6 | $8.57 |
| Gross profit on 10,000 units | $60,000 | $85,700 |
| Gross margin | 23.08% | Approximately 30% |
How Discounts Change Gross Margin
Discounts reduce selling revenue, which can reduce gross margin substantially even when the product cost remains unchanged. A 10% discount does not simply reduce a 30% gross margin to 20%. The result must be recalculated using the new selling price.
Consider a product with a $70 cost and $100 normal selling price. At the original price, the gross margin is 30%. If the business gives a 10% discount, the new selling price is $90.
New gross profit = $90 − $70 = $20.
New gross margin = $20 ÷ $90 × 100 = 22.22%.
The $10 discount reduces the dollar gross profit from $30 to $20, a one-third reduction. This is why sales promotions and volume discounts should be evaluated using the actual post-discount margin.
Gross Margin vs Net Profit Margin
Gross margin measures gross profit relative to revenue, while net profit margin measures earnings remaining after all relevant expenses and taxes. Markup is a pricing relationship, not a replacement for either accounting measure.
For example, a wholesaler may generate $500,000 in revenue and $125,000 in gross profit, producing a 25% gross margin. If operating expenses, financing costs, and taxes leave $25,000 in net income, net profit margin is 5%.
A business can therefore set apparently healthy product markups and still earn a small net margin. Warehouse costs, freight, payroll, bad debt, and financing matter alongside purchasing prices. Owners should monitor gross and net profitability rather than assuming one percentage explains the entire business.
Common Markup vs Margin Mistakes
The most common markup vs margin mistakes involve using the wrong denominator, excluding relevant costs, or applying discounts without recalculating profitability. These problems often begin when teams adopt inconsistent terminology in price lists and reporting systems.
Another mistake is assuming every SKU should have the same target margin. Different products have different demand, competitive conditions, return rates, and delivery requirements. Slow-moving products may carry more risk, while high-volume commodity items can have lower margins but attractive overall contributions.
Businesses should document a standard pricing method and verify calculations using representative transactions. They should also review actual margins after discounts, returns, and supplier cost changes. Consistent definitions help prevent disagreements between finance, sales, and purchasing teams.
Frequently Asked Questions About Markup vs Margin
Is a 30% markup the same as a 30% margin?
No. A 30% markup corresponds to a gross margin of approximately 23.08%. A 30% gross margin requires a markup of approximately 42.86%.
How do you convert markup to margin?
Divide the markup rate by one plus that rate. For example, a 25% markup converts to 0.25 ÷ 1.25 = 20% gross margin.
How do you calculate selling price from margin?
Divide the cost by one minus the target margin. A $60 cost with a 25% gross-margin target requires a selling price of $80.
Can markup be higher than 100%?
Yes. An item costing $20 and selling for $50 has a markup of 150%. Its gross margin is 60%.
Which is better for pricing, markup or margin?
Both are useful, but gross margin aligns more directly with financial performance reported as a percentage of revenue. Markup is convenient for cost-plus pricing. Businesses should understand and consistently apply both.
Does a higher markup guarantee more profit?
No. Higher prices may reduce sales volume, and operating expenses can consume gross profit. Profitability depends on actual demand, costs, and the complete business model.
Final Takeaway
Markup vs margin is one of the most important distinctions in business pricing because both measure the same gross-profit dollars from different starting points. Markup uses cost as the denominator, while margin uses selling revenue. Confusing them can result in prices below the business's intended financial targets.
Accurate pricing begins with reliable cost information and clearly defined gross-margin objectives. Business owners should verify discounts and monitor realized margins after transactions occur. The strongest pricing decisions also account for market demand, inventory requirements, and the cost of serving each customer.
Frequently Asked Questions
- Is a 30% markup the same as a 30% margin?
- No. A 30% markup corresponds to a gross margin of approximately 23.08%. A 30% gross margin requires a markup of approximately 42.86%.
- How do you convert markup to margin?
- Divide the markup rate by one plus that rate. For example, a 25% markup converts to 0.25 ÷ 1.25 = 20% gross margin.
- How do you calculate selling price from margin?
- Divide the cost by one minus the target margin. A $60 cost with a 25% gross-margin target requires a selling price of $80.
- Can markup be higher than 100%?
- Yes. An item costing $20 and selling for $50 has a markup of 150%. Its gross margin is 60%.
- Which is better for pricing, markup or margin?
- Both are useful, but gross margin aligns more directly with financial performance reported as a percentage of revenue. Markup is convenient for cost-plus pricing. Businesses should understand and consistently apply both.
- Does a higher markup guarantee more profit?
- No. Higher prices may reduce sales volume, and operating expenses can consume gross profit. Profitability depends on actual demand, costs, and the complete business model.
Written by
Marcus Hale
Marcus Hale coaches B2B sellers on conversation intelligence, pipeline hygiene, and the sales tools that change what happens after the call.
Published October 21, 2026
