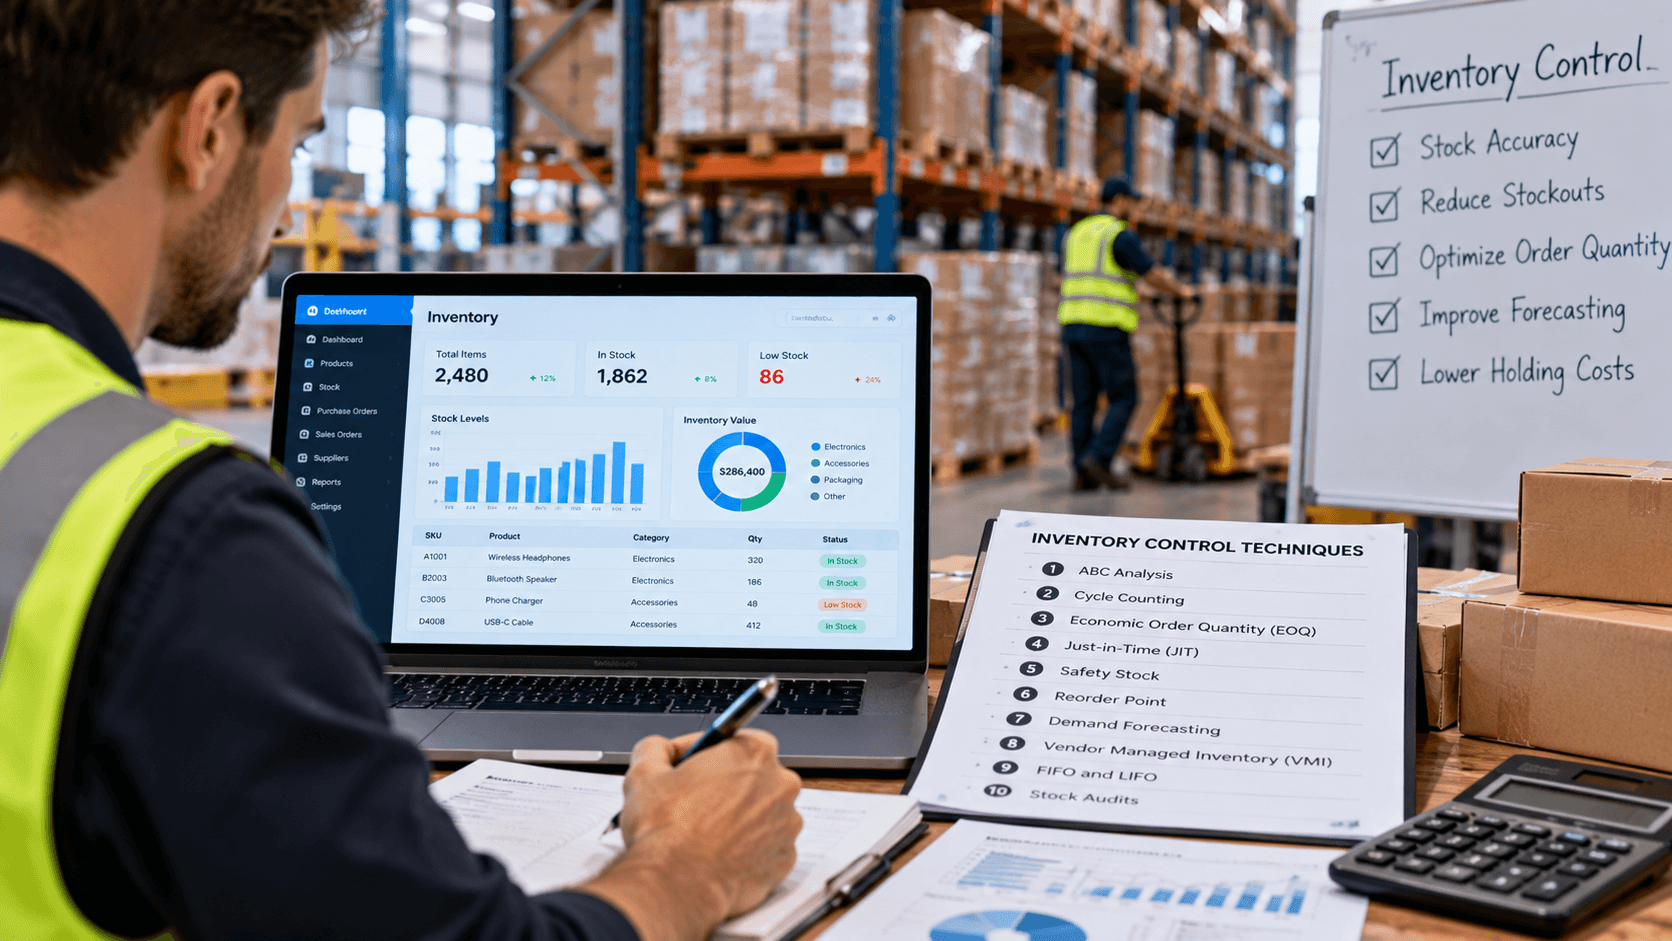
Inventory control techniques are methods businesses use to track, organize, replenish, and protect stock while balancing product availability against inventory costs. Common techniques include ABC analysis, reorder points, safety stock, economic order quantity, cycle counting, and FIFO. Each addresses a different inventory-management problem, and several methods are usually needed to operate an effective distribution business.
Inventory control is particularly important for wholesale distributors because even small mistakes can affect large quantities of merchandise. Excess inventory ties up purchasing capital and increases storage expenses, while insufficient inventory creates backorders, lost sales, and customer dissatisfaction. The challenge is maintaining the right products in the right quantities without investing more cash than necessary.
The best inventory control techniques depend on product demand, supplier lead times, margins, warehouse operations, and customer-service requirements. A fast-moving industrial component may need daily monitoring, while a slow-moving seasonal product may require tighter purchasing restrictions. Applying one method indiscriminately across every SKU rarely produces the best results.
What Are Inventory Control Techniques?
Inventory control techniques are systematic approaches to maintaining accurate stock records, determining replenishment needs, and managing inventory movement. They help purchasing and warehouse teams make consistent decisions rather than relying entirely on individual judgment. Some techniques focus on quantities and ordering, while others improve physical handling or transaction accuracy.
Inventory control is closely related to inventory management, but the terms are not identical. Inventory management covers the broader planning of product availability, financial investment, suppliers, and fulfillment. Inventory control focuses more specifically on maintaining accurate stock positions and applying practical procedures to inventory.
For example, inventory management may establish a company-wide target for working capital. Inventory control techniques help determine which products should be counted frequently, when purchasing should trigger a replenishment order, and how available stock should be allocated. The two functions should work together.
The Inventory Management for Distribution guide explains how these operating decisions connect to customer service and financial performance.
10 Inventory Control Techniques Compared
The most useful inventory control techniques address demand prioritization, replenishment timing, order quantities, physical stock movement, and record accuracy. They are complementary rather than interchangeable. A distributor may use ABC classification to prioritize attention, safety stock to manage uncertainty, and cycle counting to verify records.
A practical inventory policy defines which techniques apply to each product category. For example, the company might combine ABC analysis, perpetual records, weekly cycle counting, and statistical replenishment for critical SKUs. Slow-moving products may instead require purchasing approval and periodic stock reviews.
| Technique | Main purpose | Best application |
|---|---|---|
| 1. ABC analysis | Prioritize SKUs | Large product catalogs |
| 2. EOQ | Estimate economical ordering quantity | Stable-demand products |
| 3. Reorder point | Determine when to replenish | Replenishable inventory |
| 4. Safety stock | Protect against uncertainty | Variable demand or lead times |
| 5. Cycle counting | Verify stock accuracy | Continuous warehouse operations |
| 6. FIFO / FEFO | Control physical stock rotation | Aging and perishable inventory |
| 7. Perpetual inventory | Maintain running stock records | Frequent stock movements |
| 8. Min-max inventory control | Keep stock within defined limits | Routine replenishment |
| 9. Demand forecasting | Plan future inventory requirements | Seasonal or changing demand |
| 10. Vendor-managed inventory | Coordinate supplier-led replenishment | Established supplier relationships |
1. ABC Analysis
ABC analysis is an inventory control technique that divides products into priority groups according to a selected measure of business importance. Traditional ABC analysis often uses annual consumption value, calculated as annual unit usage multiplied by unit cost. However, distributors may also consider gross profit, stockout consequences, customer importance, or other commercial factors.
A common approach classifies a relatively small portion of products as A items because they account for a large share of the selected value measure. B items have intermediate importance, while C items contribute less to that particular metric. The exact classification percentages should reflect the company's product mix rather than arbitrary industry rules.
ABC Analysis Example
In this simplified example, SKU A-101 accounts for approximately 71% of the $141,000 annual consumption value. It therefore deserves particular attention under a consumption-value classification. However, a low-value product may still be critical if a stockout stops a customer's production line.
Distributors can improve ABC analysis by supplementing financial value with service risk. A part generating modest sales can require high priority when no suitable substitute is available. Classification should guide management effort, not replace commercial judgment.
| SKU | Annual usage | Unit cost | Annual consumption value |
|---|---|---|---|
| A-101 | 5,000 | $20 | $100,000 |
| B-202 | 2,000 | $15 | $30,000 |
| C-303 | 1,000 | $8 | $8,000 |
| D-404 | 500 | $6 | $3,000 |
2. Economic Order Quantity (EOQ)
Economic order quantity is an inventory control technique that estimates the order size minimizing the combined ordering and inventory holding costs under a defined model. It is especially useful for products with relatively stable demand and measurable purchasing costs. EOQ does not automatically account for supplier minimums, quantity discounts, or variable demand.
The classic EOQ formula is:
EOQ = √(2DS ÷ H)
Where:
- D = annual demand in units.
- S = cost of placing an order.
- H = annual inventory holding cost per unit.
EOQ Calculation Example
Suppose a wholesaler sells 12,000 units annually, incurs $75 in ordering costs per purchase, and estimates annual inventory holding costs at $4 per unit.
EOQ = √((2 × 12,000 × $75) ÷ $4)
EOQ = √450,000
EOQ ≈ 671 units
The business can use approximately 671 units as a starting estimate for the economical order size under the model assumptions. In practice, it may need to purchase in complete cases or meet supplier minimum quantities. The final purchasing decision should also reflect demand variability and available working capital.
EOQ is most useful when its assumptions are reasonably close to reality. It should not be applied without adjustment to highly seasonal, rapidly changing, or highly intermittent demand. A distributor should also evaluate quantity discounts and freight economics before adopting the calculated result.
3. Reorder Point Method
The reorder point method identifies the inventory-position level at which a new replenishment order should be triggered. It aims to place orders early enough that replacement stock arrives before existing inventory becomes insufficient. The calculation normally considers expected demand during lead time and any necessary safety stock.
Reorder point = Average daily demand × Supplier lead time + Safety stock
Assume a distributor sells 25 units per day, its supplier normally takes eight days to deliver, and it maintains 60 units of safety stock.
Expected lead-time demand = 25 × 8 = 200 units.
Reorder point = 200 + 60 = 260 units.
When inventory position reaches 260 units, the business should normally initiate replenishment under this simple continuous-review policy. Inventory position includes relevant on-hand stock, outstanding replenishment orders, and commitments such as backorders. The quantity ordered is determined separately.
This technique is particularly valuable when distributors have predictable replenishment arrangements. If demand or lead time is highly variable, a fixed reorder point may need frequent review or statistical adjustment.
4. Safety Stock Management
Safety stock management uses additional inventory to reduce the risk of shortages caused by uncertain demand or supplier delivery times. The reserve protects customer service when actual conditions differ from forecasts. However, holding too much safety stock increases storage expenses and working capital requirements.
A simple maximum-based formula is:
Safety stock = (Maximum daily demand × Maximum lead time) − (Average daily demand × Average lead time)
Suppose maximum daily demand is 50 units, maximum lead time is eight days, average daily demand is 35 units, and average lead time is five days.
Safety stock = (50 × 8) − (35 × 5)
Safety stock = 400 − 175 = 225 units.
This maximum-based method is simple but does not correspond to a defined statistical service level. More advanced techniques use standard deviations and target cycle service levels to estimate buffers under specific assumptions. The right method depends on data quality, product importance, and supplier reliability.
For a detailed explanation of the statistical approach, see the companion Safety Stock guide within the site's Logistics topic.
5. Cycle Counting
Cycle counting is an inventory control technique in which selected inventory items are physically counted on a recurring schedule. It allows a warehouse to verify records without waiting for a complete annual stock count. The objective is to detect discrepancies, investigate their causes, and improve transaction accuracy.
Cycle counting is commonly organized according to SKU importance, movement frequency, or discrepancy risk. High-priority products may be counted more frequently than stable low-value items. Locations with recurring errors can also receive additional attention.
Cycle Counting Example
A distributor manages 2,000 SKUs and establishes the following illustrative counting policy:
The policy requires 2,400 A-item counts, 2,000 B-item counts, and 1,300 C-item counts annually, for a total of 5,700 scheduled SKU counts. This is approximately 475 counts per month before recounts and exception investigations. A warehouse manager can use this workload to plan staffing and equipment.
These frequencies are examples, not mandatory standards. The right schedule depends on transaction volume, product value, historical discrepancies, and operational risk. More frequent counting is valuable only when discrepancies are investigated and the causes corrected.
| Category | Number of SKUs | Count frequency |
|---|---|---|
| A | 200 | Monthly |
| B | 500 | Quarterly |
| C | 1,300 | Annually |
6. FIFO and FEFO Inventory Rotation
FIFO and FEFO are inventory control techniques used to determine which physical stock should be issued first. FIFO means first in, first out and generally prioritizes stock received earlier. FEFO means first expired, first out and prioritizes merchandise with the earliest expiration date.
FIFO can be helpful for products affected by age, packaging changes, or gradual deterioration. FEFO is particularly important for products with expiration dates, such as certain foods, medical supplies, and chemicals. The correct method depends on product characteristics and applicable quality requirements.
FIFO vs. FEFO Example
A warehouse receives two batches of a product. Batch A arrives on October 1 and expires in December, while Batch B arrives on October 10 but expires in November.
Under a strict physical FIFO rule, Batch A would normally be issued first because it arrived earlier. Under FEFO, Batch B should be issued first because its expiration date is earlier. For expiration-sensitive products, FEFO may better reduce spoilage and customer rejection.
These physical stock-rotation methods should be distinguished from the accounting FIFO cost-flow assumption. Accounting valuation and warehouse picking are related but separate policies. Both should be documented consistently.
7. Perpetual Inventory Control
Perpetual inventory control maintains running records of stock quantities as inventory transactions are recorded. Product receipts increase the balance, while shipments, authorized write-offs, and other issues reduce it. The system can support near-real-time inventory visibility when staff consistently capture transactions.
For example, a warehouse starts with 600 units, receives 100, ships 150, and records ten damaged units as unavailable. Its resulting on-hand quantity is 540 units, assuming the transactions are recorded correctly. A perpetual inventory system reflects those changes without requiring a full warehouse count.
Barcode scanning and warehouse software can make this technique easier to operate at scale. Nevertheless, errors remain possible when transactions are skipped or entered incorrectly. Regular cycle counting is therefore an essential supporting control.
The companion Perpetual Inventory guide can be used to develop a deeper understanding of ongoing inventory records; once the standalone article is published, the internal link should be updated to its dedicated URL.
8. Min-Max Inventory Control
Min-max inventory control establishes a lower replenishment threshold and an upper target inventory level for a product. When the inventory position reaches the minimum, the business orders enough to restore it toward the maximum. This approach is relatively straightforward and useful for many regularly replenished products.
Assume a distributor sets a minimum inventory position of 150 units and a maximum of 500 units. When the inventory position falls to 140 units, a simple order-up-to policy would suggest purchasing 360 units.
Order quantity = Maximum level − Current inventory position
Order quantity = 500 − 140 = 360 units.
The actual order may need adjustment for case packs, supplier minimums, or known demand changes. Min-max levels should also be reviewed when lead times or customer orders change materially. A static policy can become inaccurate if purchasing assumptions are not updated.
9. Demand Forecasting
Demand forecasting estimates future product requirements so purchasing teams can order inventory before customers need it. Forecasts may use historical sales, recent trends, seasonality, promotions, customer commitments, and market information. Their effectiveness depends on both data quality and the method selected.
A simple moving-average forecast calculates the average demand over a chosen number of historical periods. For example, if the last three months' sales were 900, 1,050, and 1,200 units, the three-month moving-average forecast would be:
(900 + 1,050 + 1,200) ÷ 3 = 1,050 units.
This method is easy to use but may respond slowly to growth, decline, or seasonal patterns. It is not necessarily suitable for intermittent-demand products. Distributors should compare forecast accuracy against actual results and select methods according to product characteristics.
Demand forecasting is especially important when suppliers have long lead times or high minimum order quantities. Forecast errors can translate into substantial inventory investments. A good forecasting process also includes documented adjustments for known customer events and promotional activities.
10. Vendor-Managed Inventory (VMI)
Vendor-managed inventory is an arrangement in which a supplier takes an agreed role in monitoring and replenishing inventory for a customer. The customer generally shares relevant demand, inventory, or sales information, while the supplier uses that information to recommend or initiate replenishment under defined terms. Responsibilities depend on the agreement.
VMI can reduce routine ordering work and improve coordination between established trading partners. The supplier gains better visibility into demand and can potentially plan manufacturing or distribution more efficiently. The buyer may experience fewer stockouts when the arrangement works effectively.
However, VMI requires trustworthy inventory data, agreed service levels, clear ownership of replenishment decisions, and defined financial terms. It should not be assumed to mean that the supplier retains ownership of stock. VMI and consignment inventory are separate concepts, although they can sometimes be combined.
A successful VMI agreement should define minimum and maximum levels, information-sharing requirements, stockout responsibilities, order approval, payment conditions, and performance measures. Both parties need a process for resolving errors or unusual demand changes.
How to Choose the Best Inventory Control Techniques
Choosing inventory control techniques requires matching each method to product demand, supply risk, operational complexity, and business priorities. No single technique addresses every inventory challenge. A useful approach combines segmentation, replenishment planning, transaction accuracy, and physical verification.
For a small distributor with a limited product catalog, perpetual inventory records, simple reorder points, and regular cycle counts may provide sufficient control. A larger distributor may add ABC analysis, statistical safety stock, automated forecasting, and supplier collaboration. More complex methods should be introduced when they create measurable benefits.
Recommended Techniques by Business Situation
Technique selection should also consider implementation costs. Software and sophisticated forecasting models can be valuable, but they will not automatically correct poor item data or inconsistent warehouse transactions. Basic operational accuracy is the foundation for more advanced controls.
| Business challenge | Techniques to prioritize |
|---|---|
| Frequent stockouts | Reorder points, safety stock, forecasting |
| Too much slow-moving inventory | ABC analysis, EOQ, inventory reviews |
| Incorrect warehouse balances | Cycle counting, perpetual inventory |
| Expiring products | FEFO, inventory visibility |
| High ordering expenses | EOQ, supplier coordination |
| Unpredictable customer demand | Forecasting, safety stock |
| Many repetitive supplier orders | Min-max, VMI |
| Limited working capital | ABC analysis, turnover monitoring, replenishment discipline |
Inventory Control KPIs to Monitor
Inventory control KPIs help distributors determine whether their methods are improving product availability, stock accuracy, and working capital efficiency. A company should define each metric clearly and compare performance consistently across periods. Tracking too many unrelated indicators can make management less effective.
Inventory Turnover Ratio
Inventory turnover measures how often inventory is sold and replaced during a period.
Inventory turnover = Cost of goods sold ÷ Average inventory value
Suppose annual cost of goods sold is $1,200,000 and average inventory value is $200,000.
Inventory turnover = $1,200,000 ÷ $200,000 = 6 times annually.
The figure is meaningful only when compared with relevant product categories, service requirements, and previous performance. Higher turnover is not always preferable if it causes frequent shortages.
Days Inventory Outstanding
Days inventory outstanding estimates how long inventory is held before being sold.
DIO = Average inventory ÷ Cost of goods sold × Days in period
Using the same annual figures:
DIO = $200,000 ÷ $1,200,000 × 365
DIO ≈ 60.8 days.
DIO can help identify changes in inventory investment, but it should be interpreted with seasonal demand and purchasing patterns. A business that builds stock before its busiest period may temporarily report higher DIO.
Inventory Record Accuracy
Inventory record accuracy measures how well system records agree with physical stock under a defined counting method. Organizations may measure accuracy by exact SKU-location matches, acceptable tolerances, or value-based discrepancies. The selected definition should be applied consistently.
For example, if 190 of 200 counted SKU-location records exactly match their system balances, exact-match accuracy is 95%. That does not automatically mean the company has lost 5% of its inventory value. Count variance magnitude and financial exposure should be tracked separately.
Order Fill Rate
Order fill rate measures the share of demand fulfilled immediately according to a defined unit, line, or order-based metric. Businesses should specify which definition they use. Unit fill rate and complete-order fill rate can produce substantially different results.
A distributor that fills 9,500 units immediately from 10,000 units requested has a 95% unit fill rate. However, if those missing units affect many customer orders, the complete-order fill rate may be lower. Both measures can be useful for evaluating inventory availability.
Common Inventory Control Mistakes
The most common inventory control mistakes include inaccurate records, outdated reorder settings, excessive purchasing discounts, and applying identical policies to every product. These errors can produce both surplus stock and customer shortages. Reliable controls require periodic review and clear responsibility.
A frequent problem is purchasing large quantities solely to obtain a lower unit price. The resulting inventory may sell too slowly to justify its financing and storage costs. Another mistake is setting safety stock once and never updating it when demand or supplier lead times change.
Businesses may also invest in sophisticated software without defining transaction processes. If receiving, picking, returns, and adjustments are not recorded consistently, even an advanced system will report inaccurate balances. Process discipline should precede automation wherever possible.
How to Improve Inventory Control in 30 Days
Inventory control can be improved through a focused 30-day review of stock accuracy, high-priority products, purchasing policies, and replenishment performance. The objective is to correct the largest operational problems before introducing unnecessary complexity. A short implementation program can also create a baseline for measuring results.
Week 1: Measure Existing Accuracy
Select representative high-value and high-movement SKUs for physical counting. Compare their quantities with system records and document discrepancies. Review receiving and shipping transaction procedures to identify where errors arise.
Week 2: Classify Inventory
Group products by consumption value, gross-profit impact, or another documented business measure. Identify products that are critical to customers despite modest sales volume. Assign appropriate management attention to each category.
Week 3: Review Replenishment Settings
Check reorder points, safety stock, supplier lead times, and minimum quantities for the highest-priority SKUs. Compare current settings with actual sales and delivery performance. Adjust policies where historical assumptions are no longer valid.
Week 4: Establish Routine Monitoring
Introduce regular cycle counts, stockout reporting, and reviews of excess or obsolete inventory. Assign responsibility for investigating discrepancies and updating purchasing parameters. Measure progress using inventory accuracy, fill rate, and inventory investment.
A 30-day program will not solve every supply-chain problem, but it can establish stronger operating discipline. More advanced forecasting, ERP integration, or VMI arrangements can then be evaluated using clearer performance information.
Final Takeaway
Inventory control techniques help wholesale distributors maintain accurate stock levels, reduce unnecessary inventory investment, and fulfill customer orders reliably. ABC analysis prioritizes attention, EOQ and reorder points support purchasing, safety stock protects against uncertainty, and cycle counting verifies the accuracy of records. No individual method should be expected to solve every inventory problem.
The strongest inventory control process combines several compatible techniques according to product demand, financial exposure, and supplier performance. Businesses should begin with accurate data and clear warehouse procedures, then introduce more advanced tools where the benefits justify the complexity. Effective inventory control protects both customer service and the cash needed to grow a distribution business.
Frequently Asked Questions
- What are inventory control techniques?
- Inventory control techniques are methods used to track stock, maintain accurate records, and determine when and how much inventory to replenish. Examples include ABC analysis, safety stock, reorder points, EOQ, and cycle counting. Businesses often combine several methods.
- What are the most common inventory control methods?
- Common methods include ABC analysis, FIFO, FEFO, reorder points, safety stock, cycle counting, perpetual inventory, and min-max replenishment. The appropriate combination depends on product characteristics and operating requirements.
- What is the difference between inventory management and inventory control?
- Inventory management covers broader planning, purchasing, availability, and financial investment decisions. Inventory control focuses on the procedures and methods used to maintain accurate stock and guide inventory movements. The functions overlap and should be coordinated.
- Which inventory control technique prevents stockouts?
- No single technique guarantees that stockouts will never occur. Reorder points, safety stock, demand forecasting, and supplier-performance monitoring can reduce the risk when applied correctly. Their effectiveness depends on reliable information and timely execution.
- What is ABC analysis in inventory control?
- ABC analysis classifies inventory into priority groups using a selected measure, often annual consumption value. It helps businesses allocate more attention to products with greater financial or operational significance. The categories should be reviewed as product demand changes.
- Is FIFO an inventory control technique?
- Yes. Physical FIFO is a stock-rotation technique that prioritizes issuing older inventory first. It can reduce aging and obsolescence risks where appropriate. Accounting FIFO is a separate cost-flow assumption and should not be confused with the warehouse procedure.
- How can small businesses improve inventory control?
- Small businesses can begin by standardizing product records, tracking every stock movement, establishing simple reorder points, and conducting regular cycle counts. They should also review slow-moving inventory and supplier lead times. Complex software is less important than reliable procedures at the initial stage.